The Growth of Payments System in Bangladesh

1 min brief, 3 min full story
Bangladesh’s mobile financial services were expanding beyond transfers and bill payments into savings and credit, this historical payments-sector review finds. It examines how banks, wallets, payment gateways, and startups were connecting more financial activity to digital services.
From payments to embedded finance. The article discusses bank partnerships for small loans and savings, alongside credit offered through platforms such as iFarmer, Sheba, ShopUp, and Pathao. Payment gateways help merchants accept different payment methods through a connected service.
Access remains the next challenge. The analysis argues for wider inclusion and cooperation between public and private institutions as the payments system develops.
Read the full story · 3 min ↓Close the full story ↑
A Promising Landscape Fueled By A Growing Economy
Withstanding the threats posed by the worldwide pandemic, the Bangladesh economy is on an exceptional development trajectory in all of its key industries. More people now belong to the middle and affluent class (MAC), per capita income is rising, more than 63.7 percent of the population is under 25, and the government is working on digitizing the nation. With a 57 percent growth in financial inclusion between 2013 and 2018 and a 31.5 percent internet penetration rate at the start of 2022, the country has made significant strides in several development areas.
In recent years, there has been a tremendous shift in the payments landscape- payments are now quicker, simpler, and more convenient both on a local and global scale because of technological advancements. Because the present generation is tech aware and depends on online services for convenience, the country is seeing remarkable growth in digital services.
Throughout the Covid-19 pandemic, digital agility has been a key factor behind stronger revenue for all types of businesses. As more companies move their operations online, payment mechanisms have become more digitized and sophisticated.
In the last two years, the adoption of digital payments has risen dramatically. This can be seen in the rise of MFS, debit/credit payment cards, and e-banking transactions between FY 2020 and FY 2021. MFS transactions grew by more than 46 percent in just two years, while internet banking transaction values surged by 59 percent. At the same time, debit card transactions have achieved a staggering 175 percent growth while credit card payments have increased by 53 percent.
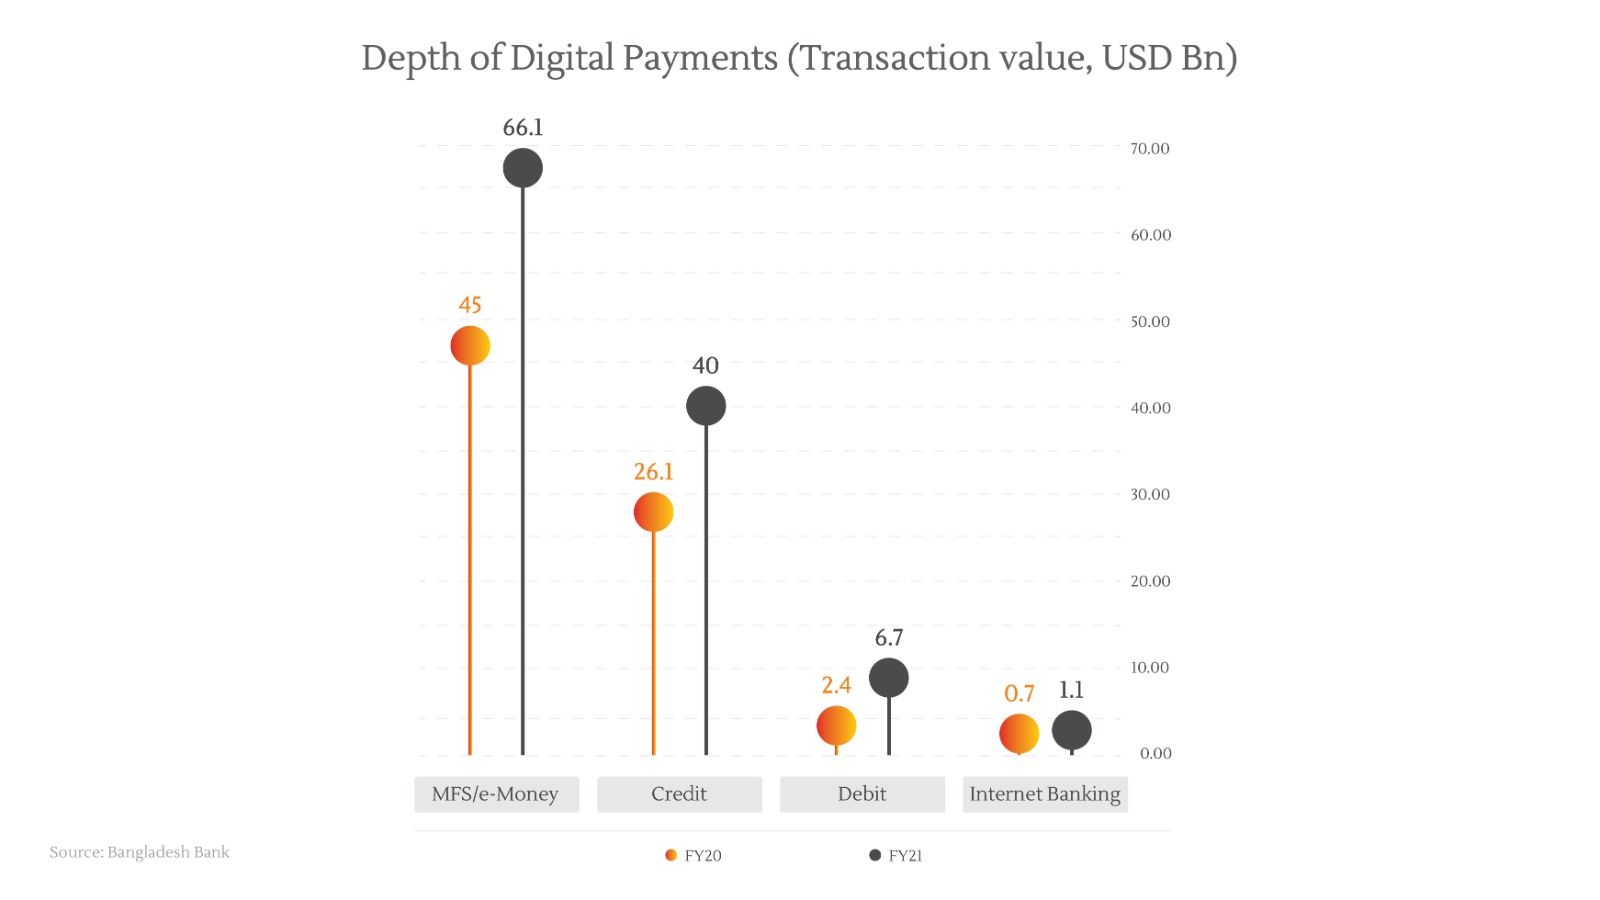
Figure: Depth of digital payments in Bangladesh
Regulatory authorities have taken notice of this and are working to address how regulations need to adjust to accommodate these modifications. In recent years, Bangladesh Bank has taken steps such as establishing the Regulatory Fintech Facilitation Office (RFFO) to create a supportive environment for Fintech and digital financing initiatives in the country. Moreover, the upcoming Interoperable Digital Transaction Platform (IDTP) will bring a variety of financial service providers under one umbrella. This will enable customers to access various financial and payment services on one platform.
What’s New?
The pandemic and the increasing digitalization have forced all stakeholders to rethink the payments ecosystem. Traditional financial institutions are adapting to new digital products and services while Fintech players are emerging to innovate the structure–easing payments for the consumers while enabling the inclusion of the unbanked and underserved.
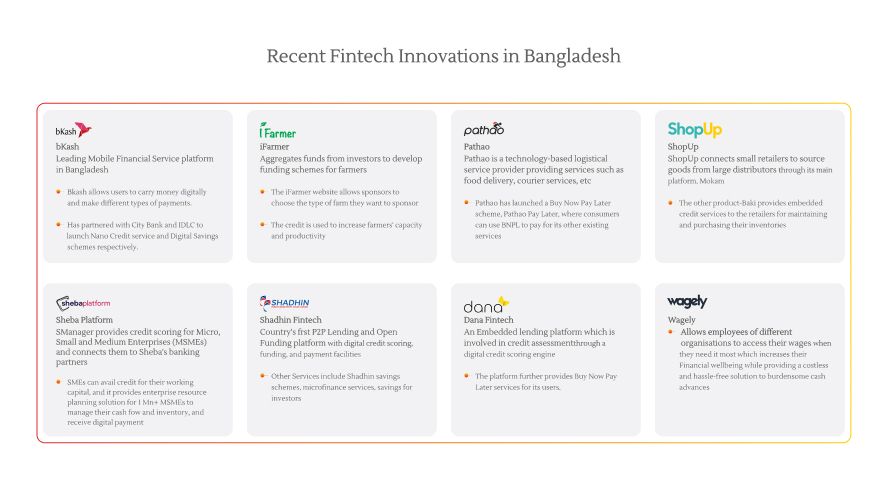
With MFS now being established among the customers, operators such as Bkash are integrating all kinds of services (Send Money, Add Money, Pay Bill, Mobile Recharge, Payment, etc) within one platform — recently partnering with banks and non-bank institutions to launch nano lending and micro-saving facilities. This enables consumers to use the mobile wallet beyond payments and access formal financing at acceptable interest rates and without collateral.
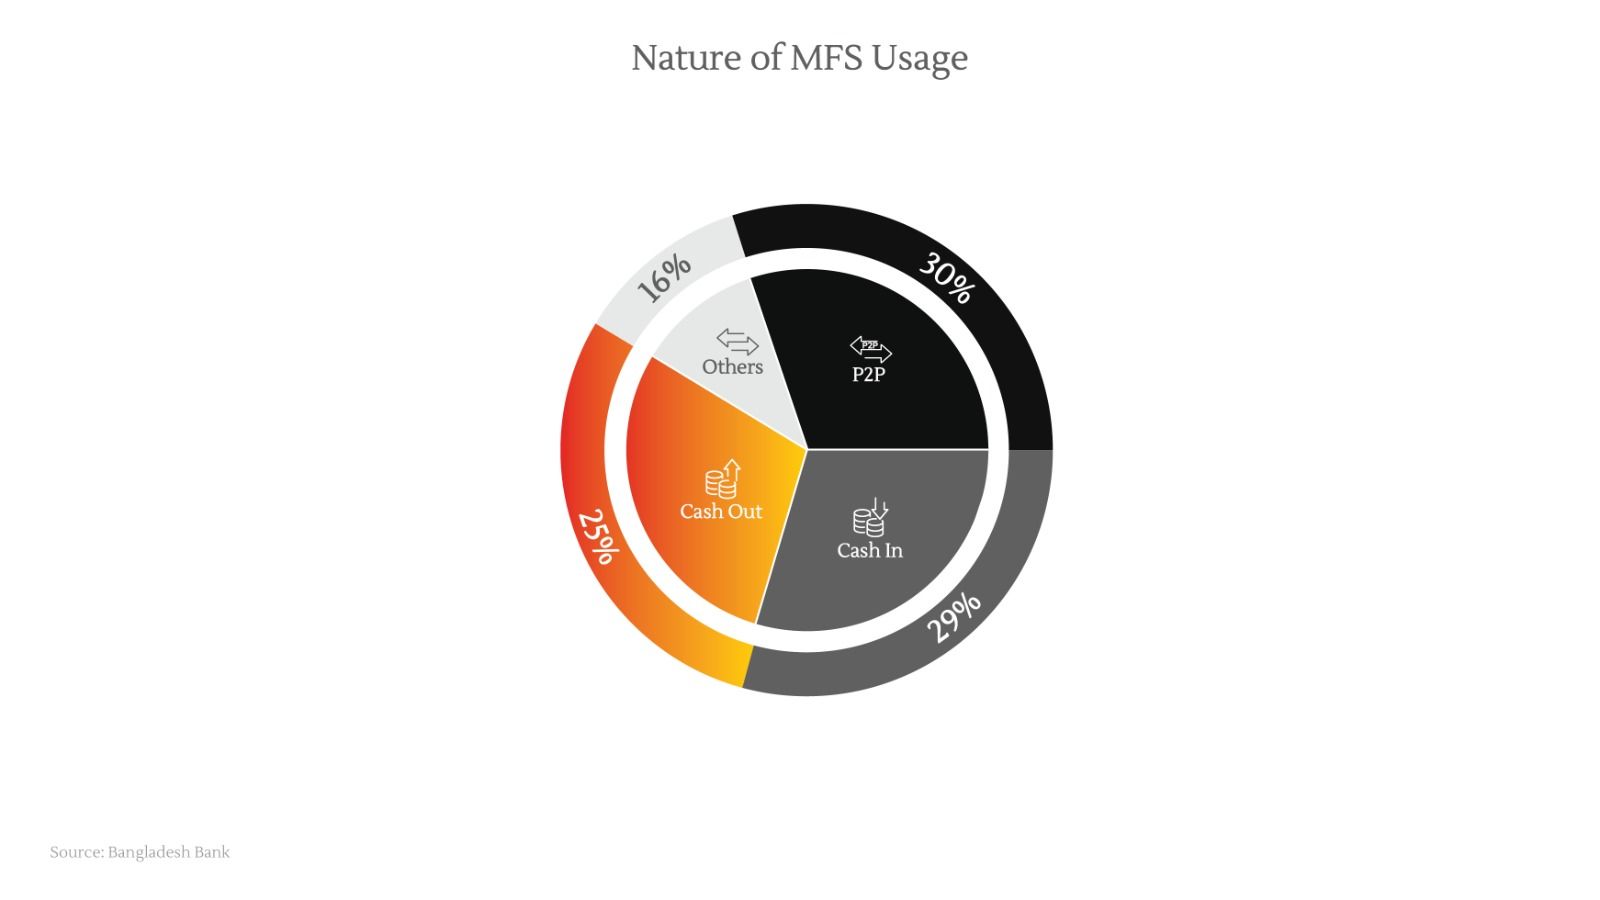
Furthermore, startups are providing embedded financial services to digitize their payments and introducing innovative products such as Buy Now, Pay Later (BNPL) within their services. Startups such as iFarmer, Sheba Platform, ShopUp, and Pathao provide digital credit services to their customers which can be used to avail the products and services. Apart from providing credit, Fintech players such as Dana and Shadhin are introducing digital credit scoring, funding, and payment facilities.
In the past two years, most large and medium-sized shops have quickly adapted to digital POS systems and almost all e-commerce and online businesses have integrated the use of digital payments through debit/credit cards, bank transfers, and MFS payments. Payment gateway systems such as PSO and PSP have played a huge role in aggregating these payments for online merchants.
What’s Next?
So far, Bangladesh has made remarkable progress in developing payment services such as MFS. However, there is room for improvement, and increasing access to financial services for the masses is key. By overcoming the barriers to financial inclusion and recognizing the opportunities, the payments system can be improved significantly. Going forward, active public-private partnerships and catering to inclusive payment services are a must to bolster this ever-growing payment system.